Guides · Transfer Problems
Why Is My International Bank Transfer Taking So Long? Where It's Stuck and What to Do
The money usually crosses borders in minutes. It's the steps before and after that take the time. Here's how to find out where yours is and how to move it along.
Quick answer
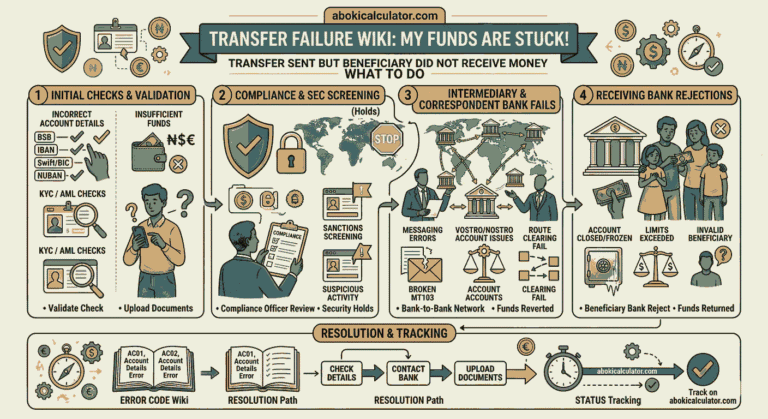
An international transfer is usually slow for one of three reasons: it's waiting at your bank (cut-off times, weekends, holidays or checks on you), at an intermediary bank (screening or missing routing details), or, most often, at the recipient's bank, which has received it but hasn't credited the account yet.
The journey between banks is normally fast. Swift reports that 90% of cross-border payments on its network reach the recipient's bank within an hour, yet only 43% are in the recipient's account within an hour. The last step is where most of the waiting happens.
What to do: get the payment's UETR (its tracking reference) from your bank and ask for its tracker status. That tells you where it is and who needs to act.
On this page
The three places a transfer waits
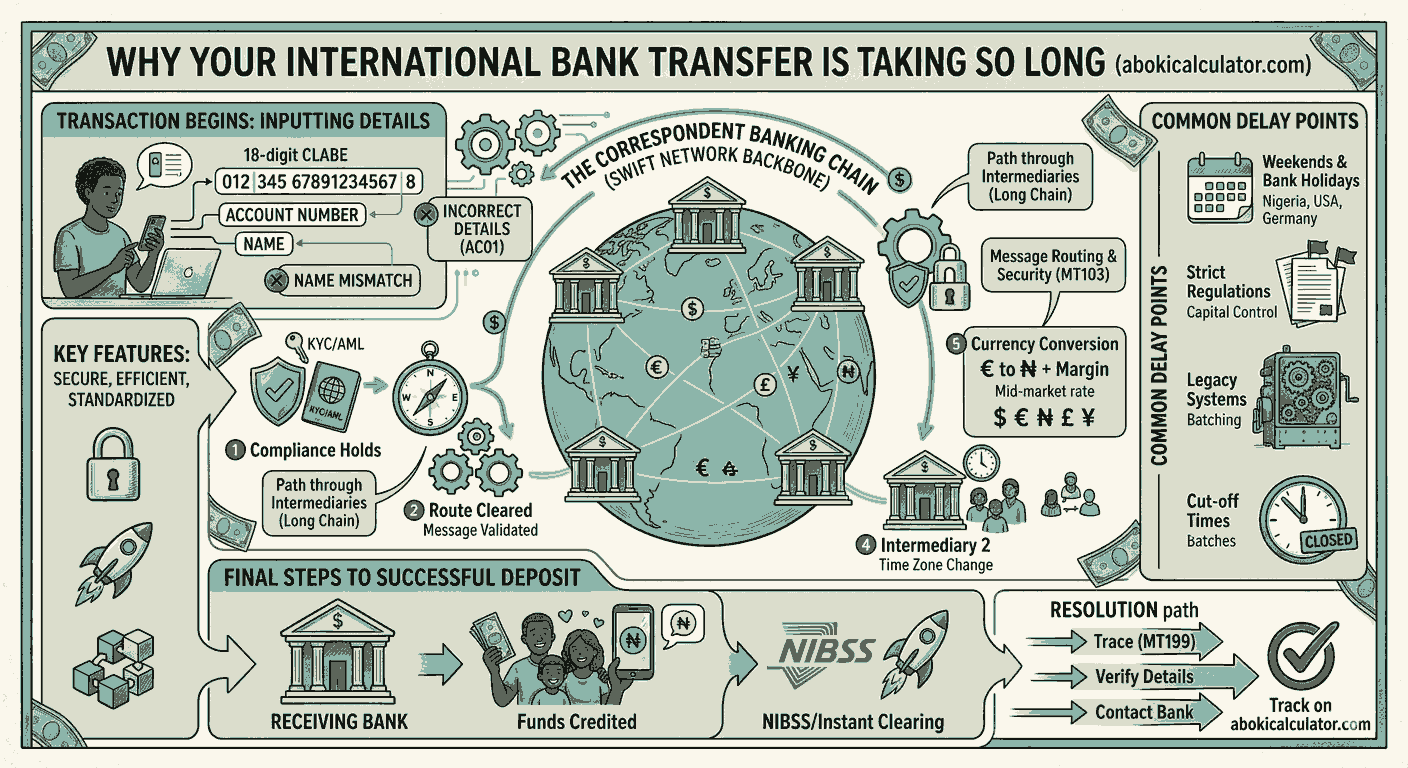
- At your bank, before it leavesYour bank must accept the instruction, check it, convert the currency if needed, and send it before its daily cut-off. Weekends, public holidays and questions about you or the payment all hold it here.Often a cause of delay
- Between banks ("in flight")The payment travels over Swift, sometimes through an intermediary bank. Swift says 75% of its payments reach the destination bank within 10 minutes, and 86% go direct or through just one intermediary.Usually fast
- At the recipient's bank ("the last mile")The recipient's bank has the payment but hasn't credited the account yet. Swift's data shows this is where most delays happen, because of back-office batch processing, local payment-system hours, regulatory and currency controls, or checks with the customer.Most common cause of delay
Why this matters: once the tracker shows the payment has reached the recipient's bank, chasing your bank won't speed it up much. The recipient usually needs to contact their bank.
How long is normal?
There is no single standard. It depends on the provider, the route, the currencies and the countries. Your provider's own estimate is the best guide, and it should give you one. In the US, remittance providers must tell you the date the money will be available.
Here is what the latest official data shows worldwide:
| Type of payment | Within 1 hour | Within 1 business day |
|---|---|---|
| Remittance services (money sent home) | 54.4% | not shown |
| Other retail payment services (people and businesses) | 35.4% | 67.3% |
| Large bank-to-bank payments ($100,000+) | 54.6% | 93.2% |
The G20 target is for 75% of cross-border payments to reach the recipient within one hour by the end of 2027. So a transfer that takes a day or two is slow compared with that goal, but it's still common today.
The causes, stage by stage
Before it leaves your bank
- Cut-off times. Instructions received after your bank's daily cut-off wait for the next business day.
- Weekends and public holidays, in your country, the recipient's country, or the country of the currency (for example, a US holiday for a dollar payment).
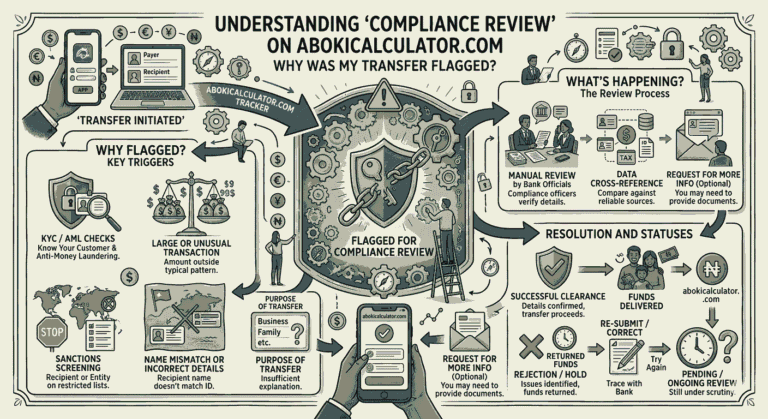
- Checks on you and the payment. Large or unusual payments may trigger questions, such as where the money came from. See why your bank may ask for source of funds.
- Currency conversion, if your bank converts the money before sending it.
Between banks
- Sanctions and anti-money-laundering screening. A name that partly matches a sanctioned person or company can pause the payment while a person reviews it.
- Missing routing details, such as an intermediary or account-with bank. See the field 56 and field 57 errors. Our correspondent bank checker shows whether your payment is likely to use one.
At the recipient's bank
- The bank needs documents from the recipient before it will credit the account, such as the payment's purpose or proof of the relationship.
- The bank is waiting for the funds. Some payments travel as an instruction plus a separate "cover" payment, and the bank waits for both.
- Batch processing and local payment-system hours. The bank may credit incoming payments only at set times.
- Currency or capital controls and local regulatory checks.
- A name or account that doesn't match. The bank may investigate first, and may send the money back. See why SWIFT payments are returned.
What your tracker status means
Most banks can see a payment's status on the Swift gpi tracker using its UETR. Ask your bank for the status and any reason code:
| Status | Where it is | Who should act |
|---|---|---|
ACSP / G000 | Passed to the next bank, moving normally | Nobody yet. Wait for the estimated date. |
ACSP / G001 | Passed to a bank that doesn't report to the tracker, so updates may stop | Your bank, if it's late: ask it to trace the payment |
ACSP / G002 | Credit pending, can't be completed the same day | Wait. If it goes on too long, ask your bank to trace. |
ACSP / G003 | Recipient's bank is waiting for documents | The recipient: they must contact their bank |
ACSP / G004 | Recipient's bank is waiting for the funds (cover payment) | Your bank: ask it to confirm and trace the cover payment |
ACCC | Credited to the recipient's account | The recipient, if they can't see it: ask their bank to check the account |
RJCT | Rejected | Your bank: get the reason code and fix the cause |
Find your UETR and write a trace request
Paste your payment confirmation or message, and our SWIFT payment tracker finds and checks the UETR, explains the status and reason codes, and writes a trace request you can send to your bank. It runs in your browser and doesn't connect to Swift.
Open the SWIFT payment trackerWhat to do, in order
- Check the estimate you were given, counting only business days in both countries. If it hasn't passed yet, the payment is probably still moving normally.
- Get the UETR and your payment confirmation from your bank or app. Check the recipient's name, account number or IBAN, and SWIFT code on it for mistakes.
- Ask your bank for the tracker status, and specifically for the international payments team if the first person you speak to can't see it.
- Act on the status. If the payment has reached the recipient's bank, or the status is
G003orACCC, the recipient should contact their bank and quote the UETR. If it's stuck at an earlier bank, ask your bank to raise a trace. - Respond quickly to any questions from either bank about the purpose of the payment or the source of funds. Unanswered questions are a common reason payments sit still, and eventually come back. See compliance reviews.
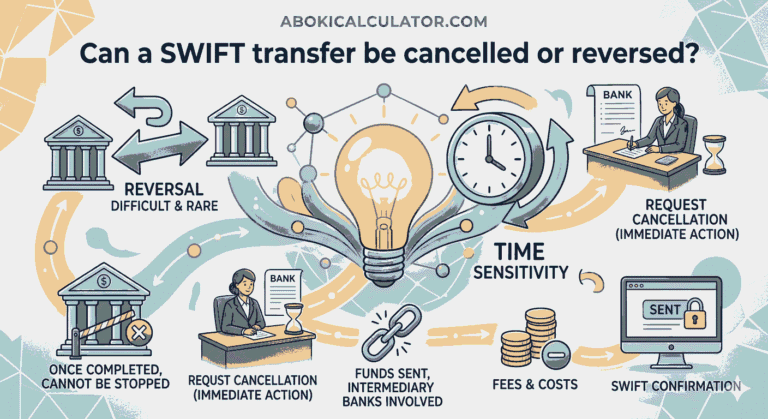
- Want to stop it? Ask your bank about a recall. It can only request one, and it isn't guaranteed once the money has been credited. See whether a SWIFT transfer can be cancelled.
Don't send the payment again while the first one is still in progress. You could end up paying twice. And be wary of anyone who contacts you about a "stuck" payment asking for a fee to release it. Banks don't release payments that way.
Your money and exchange rate while you wait
- The money is with a bank in the chain, not lost. If it's rejected or returned, it comes back to you, possibly less charges.
- The exchange rate depends on who converts it. If your bank converted the money before sending, that rate is already fixed. If the recipient's bank converts it, the rate is usually the one on the day it's credited, so a delay can change the final amount.
- Charges already deducted stay deducted, even if the payment is slow.
To see what a different rate would mean in naira, compare today's figures on our official vs black market exchange rate page.
Make the next one faster
- Send early on a business day, well before your bank's cut-off, and avoid the days before public holidays in either country.
- Get the details exactly right: the name as the bank holds it, and the account number or IBAN and SWIFT code. Check them with our SWIFT code checker, IBAN validator or NUBAN validator, and use What Bank Details Do I Need? for the full list.
- Give a clear purpose for the payment and have documents ready for large amounts.
- Ask the provider for its expected delivery time before you pay, and compare providers on speed as well as cost.
For Nigerian users
- Bank wires into Africa are among the slowest. The Financial Stability Board reports that Africa was the slowest region for receiving large bank-to-bank payments, with 24.2% credited within an hour in early 2025, up from 20.4% in 2023.
- Remittances into sub-Saharan Africa are among the fastest. The same report finds sub-Saharan Africa the fastest region for receiving remittances through remittance services, though costs remain high.
- Sending out of the region has slowed. For payments between people sent from sub-Saharan Africa, the share credited within a day fell sharply in 2025.
- If your bank asks you for documents before crediting an incoming foreign payment, reply quickly. That's often the whole delay.
- Money sent through a money transfer company is paid out in naira under CBN rules and follows a different route from a bank wire. See how international money transfers work.
Related questions
How long should an international bank transfer take?
There is no single standard: it depends on the provider, route, currencies and countries, so use your provider's own estimate. In 2025, the Financial Stability Board found that 35.4% of retail cross-border payment services credited recipients within an hour and 67.3% within one business day, while 54.4% of remittance services made funds available within an hour.
Where is my money while the transfer is delayed?
It is held by one of the banks in the payment chain: your own bank, an intermediary bank or, most often, the recipient's bank, which has received the payment but not yet credited the account. It is not lost. If the payment is rejected or returned, it comes back to you, possibly minus charges.
What is a UETR and how do I get it?
The UETR (Unique End-to-End Transaction Reference) is a 36-character reference that follows a SWIFT payment from bank to bank. Your bank or payment app can give it to you, and it may appear on your payment confirmation. With it, banks can check the payment's status on the Swift gpi tracker.
The tracker says ACCC but the recipient has not got the money. What now?
ACCC means the recipient's bank reports the money as credited to the account. The recipient should contact their bank, quote the UETR, and ask it to check which account was credited and whether any hold applies.
Will a delay change my exchange rate?
It depends on who converts the money. If your bank converted it before sending, the rate is already fixed. If the recipient's bank converts it, it usually applies the rate on the day it credits the account, so a delay can change the amount received.
Should I send the money again?
No, not while the first payment is still in progress, or you could pay twice. Find out where it is using the UETR. If you want it stopped, ask your bank to request a recall, which is not guaranteed once the money has been credited.
Why are transfers to Nigeria slow?
The Financial Stability Board reports that Africa was the slowest region for receiving large bank-to-bank payments in early 2025, with 24.2% credited within an hour, mainly because of delays after the money reaches the receiving country. Remittances into sub-Saharan Africa through remittance services were among the fastest in the world, though costs remain high.
Keep going
Sources
- Swift, Swift data shows focus needed on beneficiary leg for faster international payments (17 October 2024): 90% reach the destination bank within an hour, 43% end to end, 86% direct or with one intermediary, and the causes of last-mile delays.
- Swift, Who we are: 75% of Swift payments reach the destination bank within 10 minutes. Checked 24 September 2026.
- Financial Stability Board, G20 Roadmap for Enhancing Cross-border Payments: consolidated progress report for 2025 (9 October 2025): speed KPIs, regional findings.
- Financial Stability Board, G20 targets for enhancing cross-border payments (75% within one hour by end-2027).
- Consumer Financial Protection Bureau, Remittance Transfer Rule small entity compliance guide (disclosure of the date funds will be available).
- Tracker status and reason codes, as sourced and explained on our SWIFT payment tracker.
This guide explains why international transfers can be delayed. It is not financial or legal advice. Each bank and provider sets its own cut-off times, checks and procedures, so ask your bank about your specific payment.