Guides · Transfer Problems
Why Was My SWIFT Payment Returned? Causes, Codes and How to Get It Right Next Time
A returned payment is almost always fixable. Here's how to find out exactly why it bounced, why less money may come back, and what to check before you send it again.
Quick answer
A SWIFT payment is returned when a bank along the way, usually the recipient's bank or an intermediary bank, can't or won't complete it and sends the money back. The most common reasons are a wrong or closed account, a name that doesn't match the account, a wrong bank code, missing information (such as the recipient's address or the payment's purpose), or a compliance or sanctions concern.
Your money isn't lost: it comes back through the banks that handled it. But less may come back than you sent, because banks can deduct charges and the money may be converted twice.
What to do: ask your bank for the return reason code and the payment's UETR (its tracking reference), fix the exact detail that caused the return, and only then send again.
On this page
Rejected vs returned: why it matters
Banks use two different messages when a payment fails, depending on whether the money had already moved between them:
| Rejected | Returned | |
|---|---|---|
| When | Before the money has settled with the next bank | After the money has settled, or even after it reached the account |
| Message banks use | A status report (pacs.002, status RJCT) | A payment return (pacs.004) |
| What it usually means for you | The payment stopped early. The money usually comes back more simply. | The money has to travel back through the banks that handled it. Charges and a second currency conversion are more likely. |
| Reason given? | Yes, a reason code | Yes, a return reason code, plus any charges and exchange rate |
Industry guidance from the Payments Market Practice Group, published by Swift, says a return must carry the payment's original UETR. It must also show the charges if the amount returned differs from the amount sent, and the exchange rate if the currency differs. So your bank should be able to tell you exactly why it came back and what was taken off.
The most common causes, with their codes
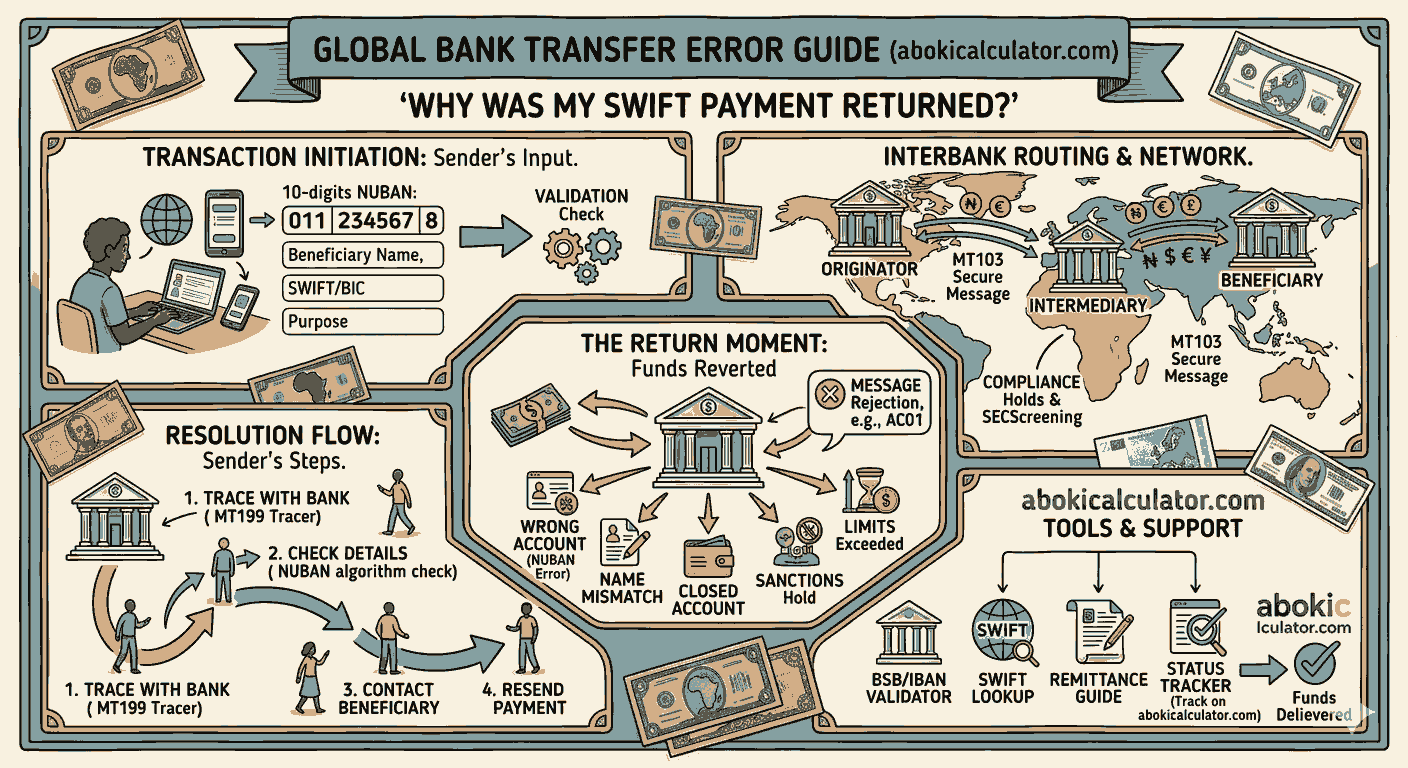
Banks give a reason as a four-character code. Here are the ones you are most likely to be told, and what to do about each:
| Code | What it means | What to fix |
|---|---|---|
AC01 | Account number or IBAN is wrong or missing | Get the number again from the recipient, in writing, and check the format |
AC04 | The account is closed | Ask the recipient for an account that is open |
AC06 | The account is blocked | The recipient must ask their bank why |
BE01 | The name doesn't match the account | Use the recipient's name exactly as their bank holds it |
RC01 | The bank identifier (BIC/SWIFT code) is wrong | Check the recipient bank's SWIFT code with the bank |
RC08 | A local routing or bank code isn't valid | Check the country's local bank code, if one was needed |
RR03 | The recipient's name or address is missing or incomplete | Add the full name and address |
RR05 | Regulatory or reporting information is missing or invalid | Ask your bank which information the destination needs |
FF07 | The purpose of the payment is missing or invalid | State the purpose clearly, as the bank asks |
AM06 | The amount is below the bank's minimum | Ask about the minimum amount |
DUPL | It looks like a duplicate payment | Check whether the first payment went through |
FOCR | Returned because someone asked to cancel it | Ask your bank who requested the cancellation |
CUST | The recipient asked for it to be rejected | Ask the recipient why |
MS03 | A bank gave no specific reason | Ask your bank to request the reason from the returning bank |
Code descriptions follow the ISO 20022 external code list, as explained on our SWIFT payment tracker. Other causes don't always come with a clear code:
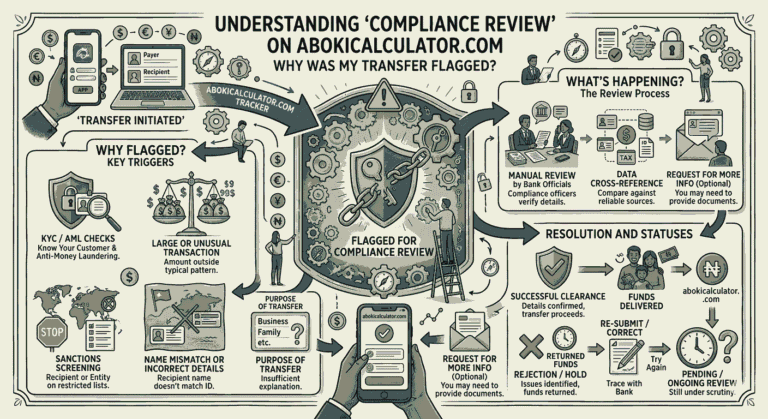
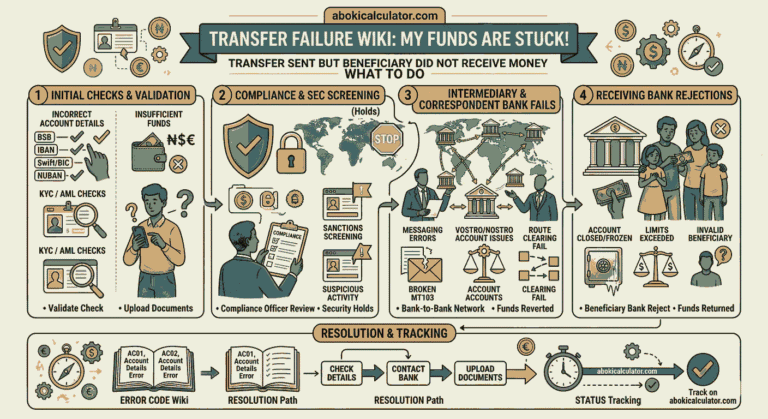
- Compliance or sanctions concerns. A bank may return a payment it can't clear under anti-money-laundering or sanctions rules, sometimes after asking questions it didn't get answers to. It may not be allowed to tell you much. See what a compliance review means.
- Routing problems. An intermediary bank may be unable to pass the payment on, for example because a correspondent bank's details were missing. See the field 57 and field 56 errors.
- Currency the account can't take. Some accounts can't receive a particular currency, and the bank may return the payment rather than convert it.
Why less money came back
Three things can shrink a returned payment:
- Charges: banks that handled the payment on the way out, or on the way back, may deduct a fee. A proper return has to show these charges.
- Converting twice: if your money was converted into another currency, it's converted back on return, at a different rate and with the bank's margin on both conversions.
- Your own bank's fees: some banks charge for handling an incoming return. Check your bank's price list.
| Step | Amount |
|---|---|
| You send $1,000, converted at €0.90 per $1 | €900 sent |
| The payment is returned, minus €15 of bank charges | €885 comes back |
| Your bank converts it back at €0.92 per $1 | 885 ÷ 0.92 |
| Credited to your account | $961.96 |
You lose $38.04: about $16.30 in charges (€15 at €0.92) and about $21.74 because the rate you sold euros back at was worse than the rate you bought them at. Nobody made a mistake with the maths. It's the cost of converting twice. Ask your bank which rate and charges it applied, so you can check the figures.
How long a return takes
There is no fixed standard time. It depends on:
- whether the payment was rejected early or returned after settling, since returns travel back through more steps;
- how many banks handled it, and their working days, time zones and public holidays;
- whether the returning bank first investigated, for example by asking the recipient or its compliance team for information;
- how quickly your own bank matches the returned money to your account.
Ask your bank for the expected date the money will be credited back, in writing. If it passes that date, ask it to trace the return using the UETR. Our SWIFT payment tracker helps you find and check the UETR and writes the trace request for you.
What to do now, step by step
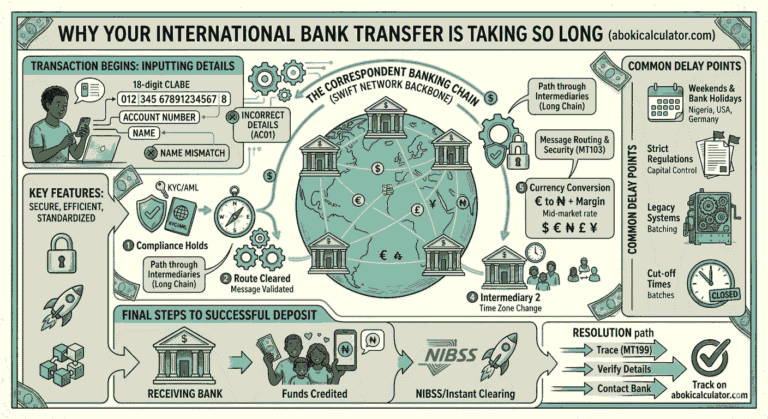
- Confirm with your bank that it's a return. A payment that is only delayed or on hold isn't the same thing. See why a transfer is taking so long.
- Get three things from your bank: the return reason code, the UETR, and the amount, charges and exchange rate of the return. Ask the international payments team if front-line staff can't see them.
- Tell the recipient, and fix the exact cause. Ask them to confirm the details that caused the return, in writing, and to check with their own bank if it's a name, currency or compliance issue.
- Wait for the money before you resend, unless you can afford to have two payments in flight. Resending with the same wrong details simply earns a second return and a second set of charges.
- Resend with the corrected details, and keep the new UETR.
Be careful of "new bank details" requests. If a returned payment is followed by an email or message asking you to pay a different account, confirm it by phone on a number you already know. Fraudsters use returned payments as a cover story.
Before you resend: checklist
- Name exactly as the recipient's bank holds it, with no nicknames or shortened names.
- Account number or IBAN. Check an IBAN with our IBAN validator, or a Nigerian account number with the NUBAN validator.
- SWIFT/BIC code of the recipient's bank, confirmed by the bank. Check the format with our SWIFT code checker. A valid format doesn't prove it's the right bank.
- Local bank code, if the country needs one. See What Bank Details Do I Need?
- Intermediary or correspondent bank, if the recipient's bank asks for one. See the correspondent bank checker.
- Recipient's address and a clear purpose of payment.
- Currency the recipient's account can accept.
Get the full list of details for any country
Choose send or receive, and the recipient's country. The tool lists every detail to ask for, including SWIFT/BIC, IBAN and any local bank code, and links to the right checker.
Open What Bank Details Do I Need?Your bank gave you a message file or reference? The ISO 20022 message decoder explains what each part says.
For Nigerian users
- Receiving from abroad: give the sender your name exactly as it appears on your account, your 10-digit account number, your bank's name and its SWIFT code, and your bank's address if they ask. A mismatch between the name the sender typed and your account name is a common reason for a return.
- Dollars to a naira account? Before you give your details for a foreign-currency wire, ask your bank whether to use your naira account or a domiciliary account, and whether it needs intermediary bank details. Its instructions decide whether the payment goes through.
- Sending from Nigeria: if an outward transfer comes back, ask your bank which currency and rate the refund will be credited at, and what charges were deducted.
- Money sent through a money transfer company follows different rules and is paid out in naira. See how international money transfers work.
Related questions
Is my money lost if a SWIFT payment is returned?
No. A returned payment travels back through the banks that handled it and is credited to the sender's account. The amount can be smaller than you sent, because banks may deduct charges and the money may be converted back at a different exchange rate.
What does return reason code AC01 mean?
AC01 means the account number or IBAN is incorrect or missing, so the receiving bank could not match the payment to an account. Get the account number again from the recipient in writing, check its format, and correct it before you resend.
What does BE01 mean on a returned payment?
BE01 means the identification of the end customer is not consistent with the account number, which in practice usually means the recipient's name does not match the name on the account. Use the name exactly as the recipient's bank holds it.
Why did I get back less than I sent?
Banks that handled the payment can deduct charges on the way out or back, and if your money was converted into another currency, it is converted back at the rate on the day of the return, with the bank's margin on both conversions. Your bank should be able to show you the charges and the exchange rate applied.
How long does it take for a returned SWIFT payment to come back?
There is no fixed standard time. It depends on how many banks handled the payment, whether it was rejected early or returned after it settled, whether a bank investigated first, and on working days and holidays. Ask your bank for the expected credit date, and if it passes, ask it to trace the return using the payment's UETR.
What is the difference between a rejected and a returned payment?
A rejection happens before the money has settled with the next bank, and banks report it with a status message. A return happens after the money has settled, and the funds are sent back with a separate payment-return message that should include the reason, any charges and any exchange rate.
Should I resend the payment straight away?
Only after you know the reason code and have fixed the exact detail that caused the return. Resending with the same details usually causes a second return and a second set of charges. If you cannot afford to have two payments in flight, wait until the returned money is back in your account.
Keep going
Sources
- Payments Market Practice Group, Best Practice Guidance for the Return of Funds and Rejects of Payments (September 2023, published by Swift):
pacs.002rejects vspacs.004returns, original UETR, charge and exchange-rate information, return reason codes. - Swift, ISO 20022 for financial institutions: end of MT/ISO 20022 coexistence for cross-border payments on 22 November 2025.
- ISO 20022 external code list meanings, as explained and sourced on our SWIFT payment tracker.
This guide explains how returned international payments work in general. It is not financial or legal advice. Each bank sets its own charges, rates and procedures, so confirm the details of your payment with your bank.